
Economy
From interest rates to inflation, understand the impact of macroeconomic trends on the real estate capital markets.
The Beyond Insights series aims to deliver timely economic and market-driven insights to better inform your commercial real estate investment decisions.
Markets
From local market rents to cap rates, catch up on the latest capital markets insights.
Learn moreU.S. ECONOMIC MACRO COMMENTARY & INSIGHTS
Hope Is Not a Rate Forecast
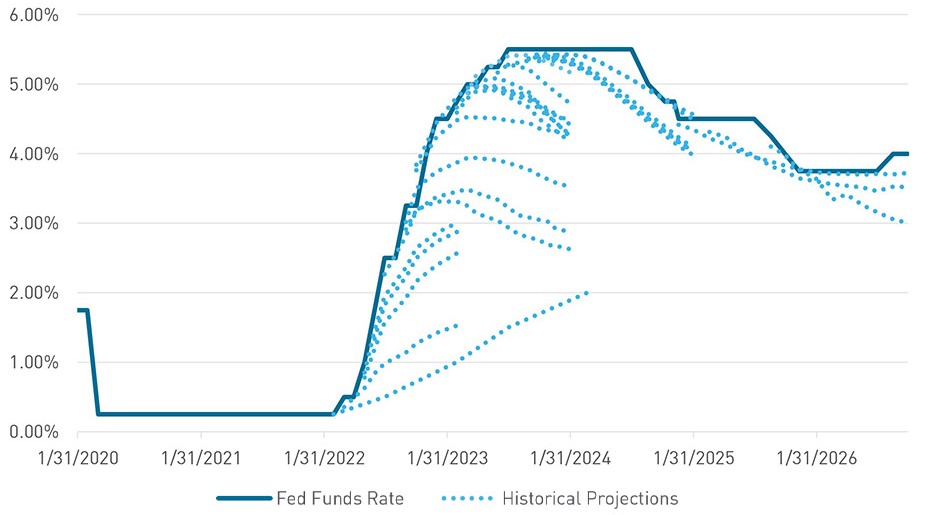
- Inflation and labor data continue to argue against near-term easing, with the market now fully pricing a December rate hike.
- The expected path of rates has moved sharply higher as the market again unwinds earlier expectations for cuts.
- For CRE borrowers, waiting for lower rates increasingly means betting that the market’s next forecast will be more accurate than its last.
Every few months, the market writes the Fed a heartfelt letter asking for rate cuts, but the Fed keeps returning it unopened. The October Consumer Price Index (CPI) rose 0.4% versus a 0.3% consensus, and core CPI rose 0.3% for a third consecutive month. Producer prices are likewise uncomfortably high, with final demand coming in at 6.5% over the 12 months, and the goods index coming in at 10.2% annually, the biggest 12-month surge since October 2022.
Fed Fund Futures at Different Points in Time
2026 Mid-Year Multifamily Pulse Survey
We surveyed more than 100 of our trusted clients across various companies for our second-annual Mid-Year Multifamily Pulse Survey with the goal of providing a comprehensive view of current market sentiment.
2026 Multifamily Investor Sentiment Survey
In December 2025, we surveyed over 250 of our trusted clients from various companies, with most holding senior-level titles, for our second annual Multifamily Investor Sentiment Survey. Our goal is to provide a comprehensive view of current market sentiments to our clients, and we plan to share our findings in our detailed report.
Hope Is Not a Rate Forecast
Every few months, the market writes the Fed a heartfelt letter asking for rate cuts, but the Fed keeps returning it unopened. The October Consumer Price Index (CPI) rose 0.4% versus a 0.3% consensus, and core CPI rose 0.3% for a third consecutive month. Producer prices are likewise uncomfortably high, with final demand coming in…
The Fed Paused, but Borrowing Costs Remain Elevated
The Federal Reserve held the federal funds rate at 3.75% to 4.00% this week, as widely expected. But borrowing costs didn’t follow. Long-term Treasury yields remain elevated, even after rallying off their recent highs, while agency spreads have moved wider. For commercial real estate, an unchanged Fed has not translated into cheaper financing. The Committee’s…
Forget Neutral. Are Financial Conditions Actually Restrictive?
The Fed raised rates in September, but the more consequential message may be that Warsh is less interested in where policy sits relative to neutral than in whether financial conditions are actually doing the job. Markets came into September focused on whether the Fed would raise rates. By the end of the press conference, a…